
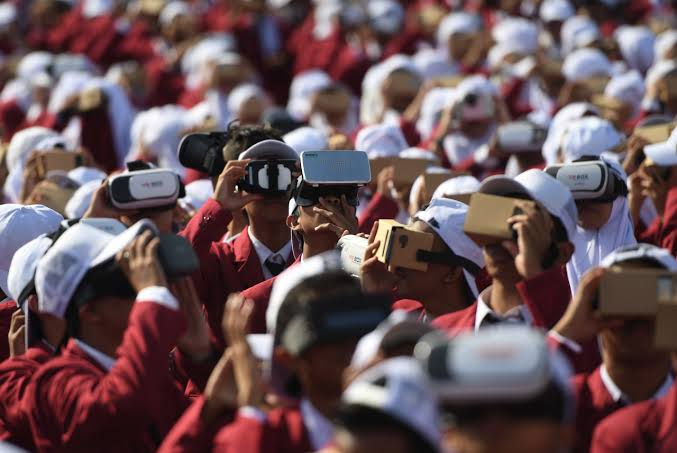
Syariah Financing For Metaverse, This time I try to evaluate the opportunities and challenges in providing Islamic financial services in the metaverse, as well as outline new financial services that are in line with the Islamic finance framework for the metaverse to address financing needs. The most critical challenge in evaluating shariah compliance financial services in the metaverse is to investigate whether virtual assets are substantially similar to physical assets and how they are evaluated.
In addition, the connection to cryptocurrencies and the associated risks and perceptions of gambling should be covered by any artificial intelligence regulations and frameworks for the Islamic metaverse. How is the financing processed in the metaverse? The metaverse has become a key component of the new digital economy representing a new virtual living environment.
Given the virtual nature of the metaverse, the various financing structures applicable to conventional Islamic finance should be analyzed how they can be applied to the metaverse. The first form of Islamic financing is the use of Ijara finance leases, which are the sharia version of conventional leases. The ijarah provisions indicate that the responsibility for maintaining assets is separated into the maintenance of large and small assets. Major maintenance of the assets belongs to the lessor, while minor maintenance belongs to the lessee.
In the case of the metaverse, Ijara will involve digital assets. This can be in the form of various digital assets such as virtual clothes or means of transportation. The main question is whether this digital asset includes a Gharar component, which makes it impermissible for investment. Gharar in Islamic finance deals with the uncertainty, fraud, and risks that may be associated with assets. In other contexts, it may be considered similar to the situation of non-existent or undetermined assets or services.
In the conventional sense, this relates to unharvested crops or fish that have not been caught. The concept of Gharar is very important in Islamic finance as it provides a measure of the legitimacy of risky investments. Primarily, it relates to short selling, gambling, and the sale of goods and assets of uncertain quality. Furthermore, any contract which cannot be expressly withdrawn can be considered Gharar. Of course, this term is rather broad and subject to interpretation.
Therefore, a sale or financial transaction is considered gharar depending on the degree of misunderstanding between the parties and the degree of uncertainty that exists in terms of delivery of the goods and payment. Its main purpose is to avoid situations that give rise to injustice or fraud against one of the parties and are generally considered a form of fraud.
The main source of Gharar can be found in the hadith, where the Prophet Muhammad underlined that one should avoid selling the birds in the sky, the fish in the water, and the unborn calf in the mother’s womb (Brown, 2017). In particular, the prophet emphasized “Do not sell what you do not have” (Sunan Ibn Majah, Hadith 2187). In particular, gharar appears when ownership claims are unclear or suspicious. Furthermore, the Qur’an states “And do not eat your wealth among yourselves for nothing.” which outlines the prohibition of predatory business practices.
In determining whether a particular asset class is classified as gharar, it is important to take a comparative approach to analyzing whether an asset or transaction is considered gharar. Derivative transactions, such as forwards, futures, and options, are mostly prohibited because they involve significant uncertainty associated with the future delivery of the underlying asset. The critical difference is between minor and substantial gharar. Speculative forwarding, such as betting on exchange rates, is clearly very gharar and prohibited. On the other hand, short-term sales of interchangeable goods, such as wheat and other commodities, where the goods are shipped at a later time are also permitted. Given that several cryptocurrency agencies are already operating in Dubai and Malaysia, cryptocurrencies are in most cases, considered permitted under Sharia law (Wilson C., 2019; McDevitt, 2021). The next challenge is how assets in the metaverse are assessed in terms of sharia compliance.
Virtual land can be considered similar to physical land as an asset in the metaverse, mimicking the evaluation of physical land (Sait & Lim, 2006). In comparison, this equivalence may, in its current form, be a matter of debate because the perception is that virtual land is more akin to software or an intangible asset than a tangible asset. There are several forms of Islamic financing options that are tailored to the needs of the metaverse.
Murabaha financing is a form of financing in which the financier will buy an asset and sell it to an entity for an amount consisting of the price of the asset in addition to the profit margin. Murabaha financing needs to be adapted to the metaverse. Next I will denote it as Meta-Murabaha. The first major parties are metafinancier and metaentity.
The metaentity can be an avatar or a digital company that is involved in a transaction with a metafinancer. Metafinanciers are digital financial service providers, such as individuals or lending companies, or digital banks in the metaverse.
The metafinancier and the metaentity then engage in a sale and purchase agreement for the digital asset, which requires the metafinancier to purchase the digital asset on a spot basis. These digital assets can come in various forms, such as digital clothing, equipment, avatars, and others. The metafinancier buys the assets from a third party, and then the metaentity pays the metafinancier in one payment or a series of incremental payments.
All these payments are made with the metaverse cryptocurrency. The whole agreement is a smart contract backed by the metaverse contract blockchain. Utilization of meta-Murabaha financing faces several challenges because it is not suitable for long-term financing.
This is due to the fact that the price will be predetermined at the time of purchase, which does not take into account changes in the cost of funds. For the metaverse, the cost of funds can increase rapidly in a short period of time if there is significant demand for services in the metaverse. Therefore, meta-Murabaha is most suitable for purchasing spot digital assets that are repaid in a relatively limited period of time.
Another form of Islamic financing in the metaverse is the commodity meta-Murabaha. Non-fungible tokens (NFT) have become one of the most valuable commodities in the metaverse. In addition, land in the metaverses is a significant commodity and has experienced a considerable increase in value. The commodity meta-Murabaha financing framework provides sharia-compliant financing options for commodities in the metaverse. In this case, the metafinancier purchases a virtual commodity, such as an NFT or other virtual, which then forms the basis of a master meta-Murabaha agreement (MMAA).
It provides long-term meta-financing without the need to acquire virtual assets and the risks associated with them. Likewise, virtual dresses can be leased on a lease basis for special occasions for avatars in the metaverse. Another form of contract is one that provides a project financing framework that conforms to Islamic principles in the metaverse. Metafinancier and metaentity enter into a meta-istisna agreement in which the metaentity will deliver the project to the metafinancier within a specified timeframe.
The metafinancier will then take the rights to the digital project upon completion, after which the meta-Ijara lease then commences, during which the metaentity will lease back and operate the project from the metafinancier. The metaverse Sukuk market is still in its early stages but will experience significant growth in the years to come. The first step in Al Ijara’s Meta-Sukuk is the formation of a meta SPV issuer who will issue the e-Sukuk in the metaverse in the form of a trust certificate representing undivided ownership interest in a particular digital asset or use of the asset which also gains rights to the revenue generated by the meta SPV of the assets.
The metaverse has become very important in recent years, becoming a virtual universe in which individuals and companies can interact. While the metaverse is still in its nascent stage, there is increasing interest and capital inflows into this universe. For sharia-focused investors and financial actors, this is a considerable challenge given the lack of an Islamic financing framework for the metaverse.
Dr.Aswin Rivai,SE.,MM
Dosen Ekonomi Moneter UPN Veteran Jakarta /Mantan Kepala Divisi Financial Institutions Bank of India Indonesia





Tinggalkan Balasan